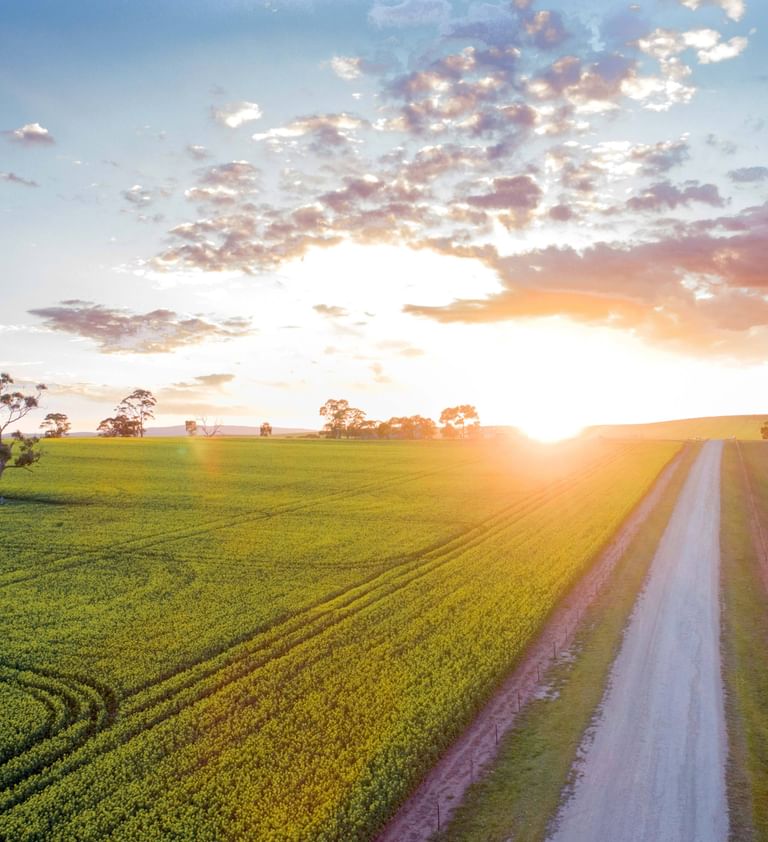


Across the country, quality continues to drive results. Blue chip holdings and neighbouring parcels are still attracting strong competition and commanding a premium, while secondary and marginal country is taking longer to sell. Higher interest rates given the Reserve Bank’s four consecutive rises this year, fuel and fertiliser costs lifted by conflict in the Middle East and uncertainty around capital gains tax reform have made it harder for many farm businesses to justify another purchase at current values. Leasing and share farming are increasingly being used to build scale and many producers are prioritising on-farm investment in water, fencing and productivity over expansion.
Livestock remains the standout support for the sector, with elevated cattle and sheep prices underpinning grazing land values across much of the country, while the grain price outlook has improved through spring.
Looking ahead, values are expected to continue lifting through the remainder of 2026 as harvest cash flow flows through to the southern cropping states and livestock markets remain firm. The outlook into 2027 is more measured, with El Niño conditions raising the likelihood of a drier season across agricultural regions and further rate rises possible. For buyers and sellers alike, the market is likely to remain selective, rewarding quality, location and water security over broad-based growth.